
Solved Assignments
College Assignment: Financial Derivatives and Hedging Strategies
- Finance
- 8 pages
- Shared May 2025
An assignment on financial derivatives, including their uses in hedging strategies in finance.
Preview · 3 of 8 pages
100%
Page 1
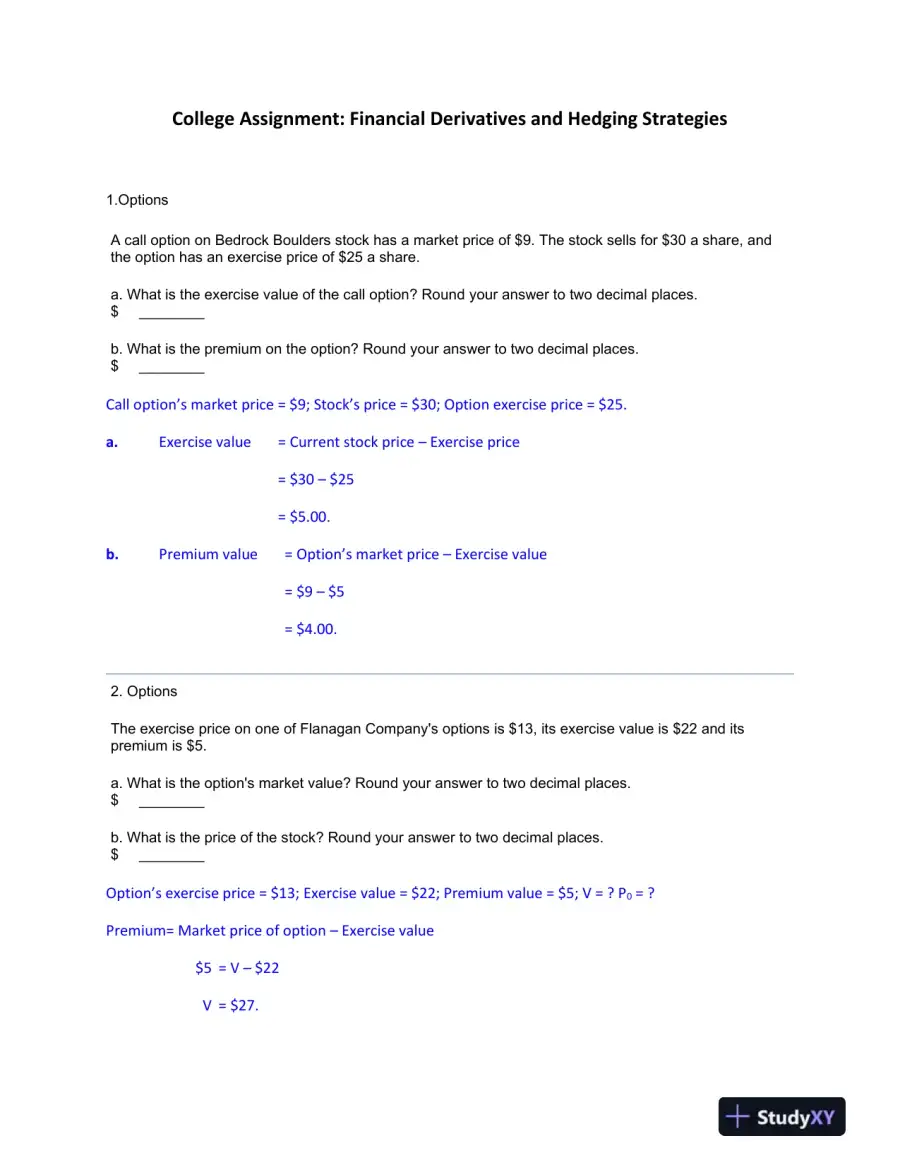 College Assignment: Financial Derivatives and Hedging Strategies1.OptionsA call option on Bedrock Boulders stock has a market price of $9. The stock sells for $30 a share, andthe option has an exercise price of $25 a share.a. What is the exercise value of the call option? Round your answer to two decimal places.$________b. What is the premium on the option? Round your answer to two decimal places.$________Call option’s market price = $9; Stock’s price = $30; Option exercise price = $25.a.Exercise value= Current stock price–Exercise price= $30–$25= $5.00.b.Premium value= Option’s market price–Exercise value= $9–$5= $4.00.2.OptionsThe exercise price on one of Flanagan Company's options is $13, its exercise value is $22 and itspremium is $5.a. What is the option's market value? Round your answer to two decimal places.$________b. What is the price of the stock? Round your answer to two decimal places.$________Option’s exercise price = $13; Exercise value = $22; Premium value = $5; V = ? P0= ?Premium= Market price of option–Exercise value$5= V–$22V= $27.
Page 2
Page 3
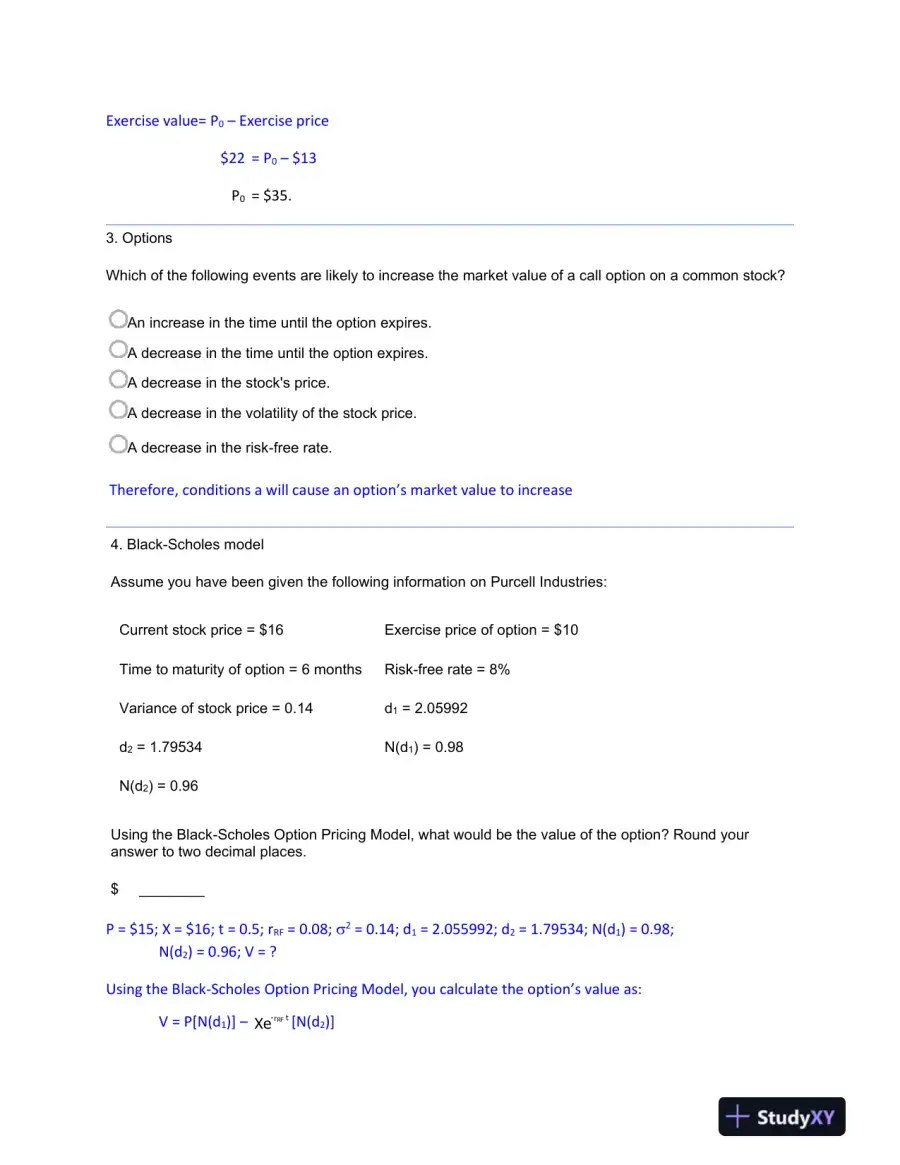 Exercise value= P0–Exercise price$22= P0–$13P0= $35.3.OptionsWhich of the following events are likely to increase the market value of a call option on a common stock?An increase in the time until the option expires.A decrease in the time until the option expires.A decrease in the stock's price.A decrease in the volatility of the stock price.A decrease in the risk-free rate.Therefore, conditions a will cause an option’s market value to increase4.Black-Scholes modelAssume you have been given the following information on Purcell Industries:Current stock price = $16Exercise price of option = $10Time to maturity of option = 6 monthsRisk-free rate = 8%Variance of stock price = 0.14d1= 2.05992d2= 1.79534N(d1) = 0.98N(d2) = 0.96Using the Black-Scholes Option Pricing Model, what would be the value of the option? Round youranswer to two decimal places.$________P = $15; X = $16; t = 0.5; rRF= 0.08;2= 0.14; d1= 2.055992; d2= 1.79534; N(d1) = 0.98;N(d2) = 0.96; V = ?Using the Black-Scholes Option Pricing Model, you calculate the option’s value as:V= P[N(d1)]–Xetr-RF[N(d2)]
5 more pages in the full document
Unlock it once and it stays in your library, ready to chat with or turn into flashcards.
Unlock the full documentMore Finance study materials
See all Textbook Guides
Solution Manual For Investments, 12th Edition
Finance
314 pages161downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, 8th Edition
Finance
851 pages158downloadsFeb 2025 Textbook Guides
Solution Manual for Financial Institutions Management: A Risk Management Approach, 8th Edition
Finance
486 pages154downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, Arab World Edition
Finance
373 pages148downloadsFeb 2025 Textbook Guides
Multinational Financial Management, Study Guide, 6th Edition Solution Manual
Finance
278 pages146downloadsFeb 2025 Textbook Guides
Financial Markets and Institutions, 7th Edition Solution Manual
Finance
194 pages136downloadsFeb 2025 Certification Guides
Wiley Finra Series 3 Exam Review (2019)
Finance
253 pages131downloadsFeb 2025 Exam Guides
Test Bank For Essentials of Investments, 8th Edition
Finance
368 pages130downloadsFeb 2025
Study this document with CramX
Once it is in your library, every tool can work from it.