
Solved Assignments
Financial Derivatives and Risk Management Assignment
- Finance
- 19 pages
- Shared May 2025
Description: This assignment explores financial derivatives and strategies for managing risk in investment portfolios.
Preview · 6 of 19 pages
100%
Page 1
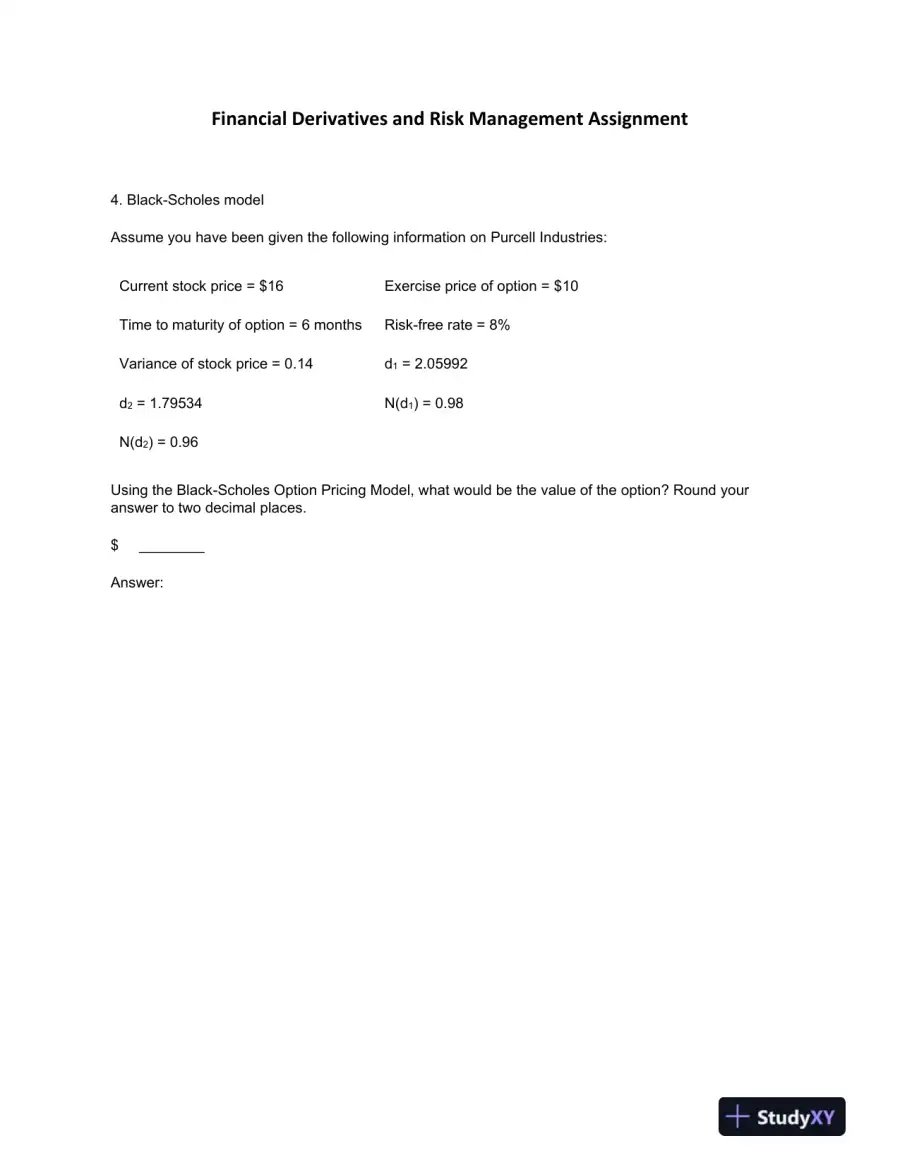 Financial Derivatives and Risk Management Assignment4.Black-Scholes modelAssume you have been given the following information on Purcell Industries:Current stock price = $16Exercise price of option = $10Time to maturity of option = 6 monthsRisk-free rate = 8%Variance of stock price = 0.14d1= 2.05992d2= 1.79534N(d1) = 0.98N(d2) = 0.96Using the Black-Scholes Option Pricing Model, what would be the value of the option? Round youranswer to two decimal places.$________Answer:
Page 2
Page 3
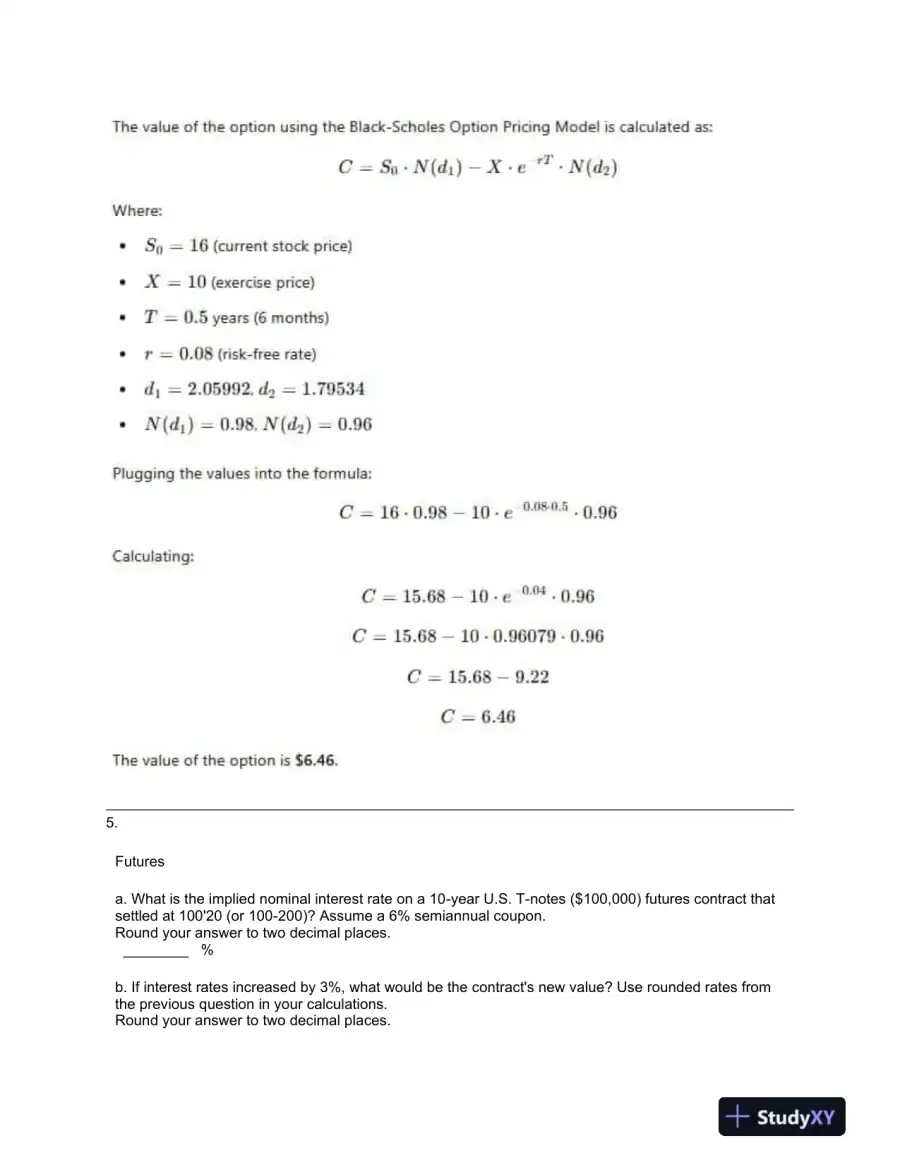 5.Futuresa. What is the implied nominal interest rate on a 10-year U.S. T-notes ($100,000) futures contract thatsettled at 100'20 (or 100-200)? Assume a 6% semiannual coupon.Round your answer to two decimal places.________%b. If interest rates increased by 3%, what would be the contract's new value? Use rounded rates fromthe previous question in your calculations.Round your answer to two decimal places.
Page 4
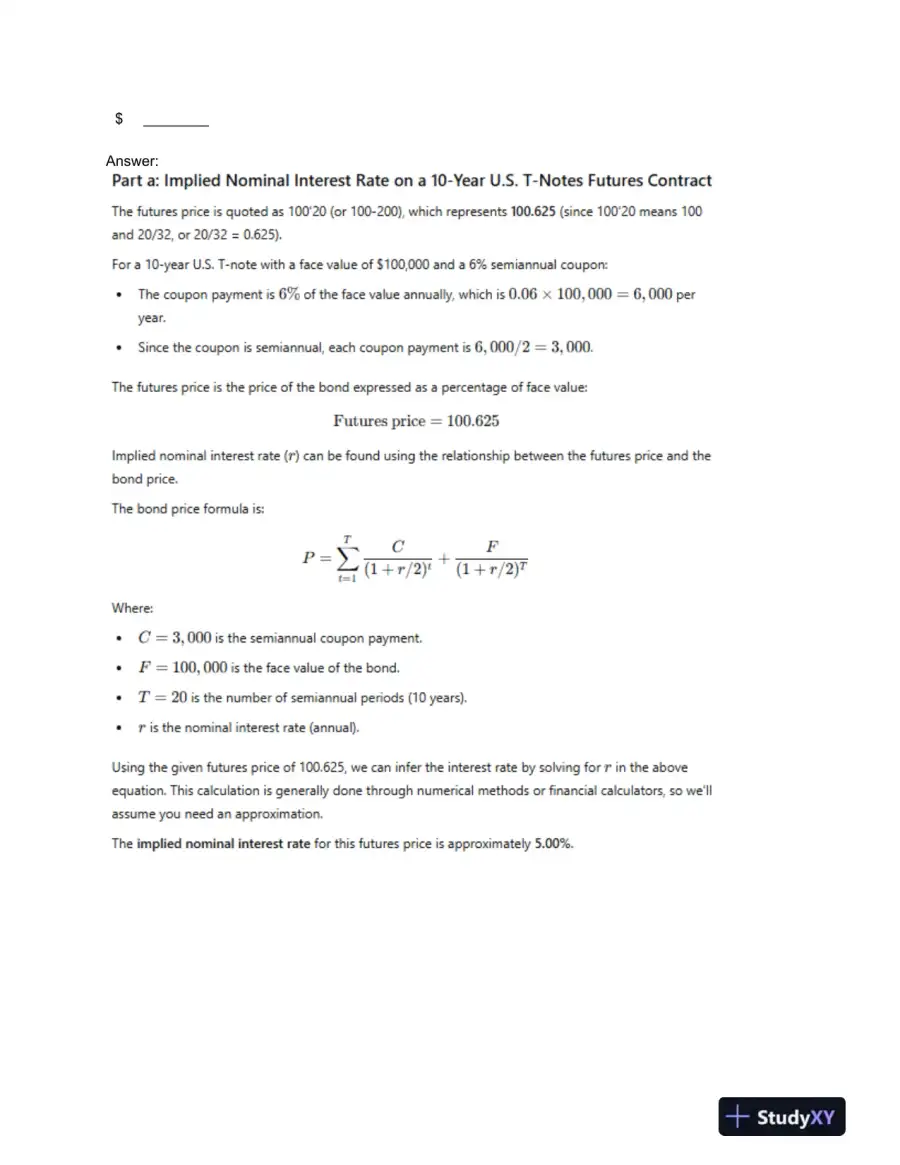 $________Answer:
Page 5
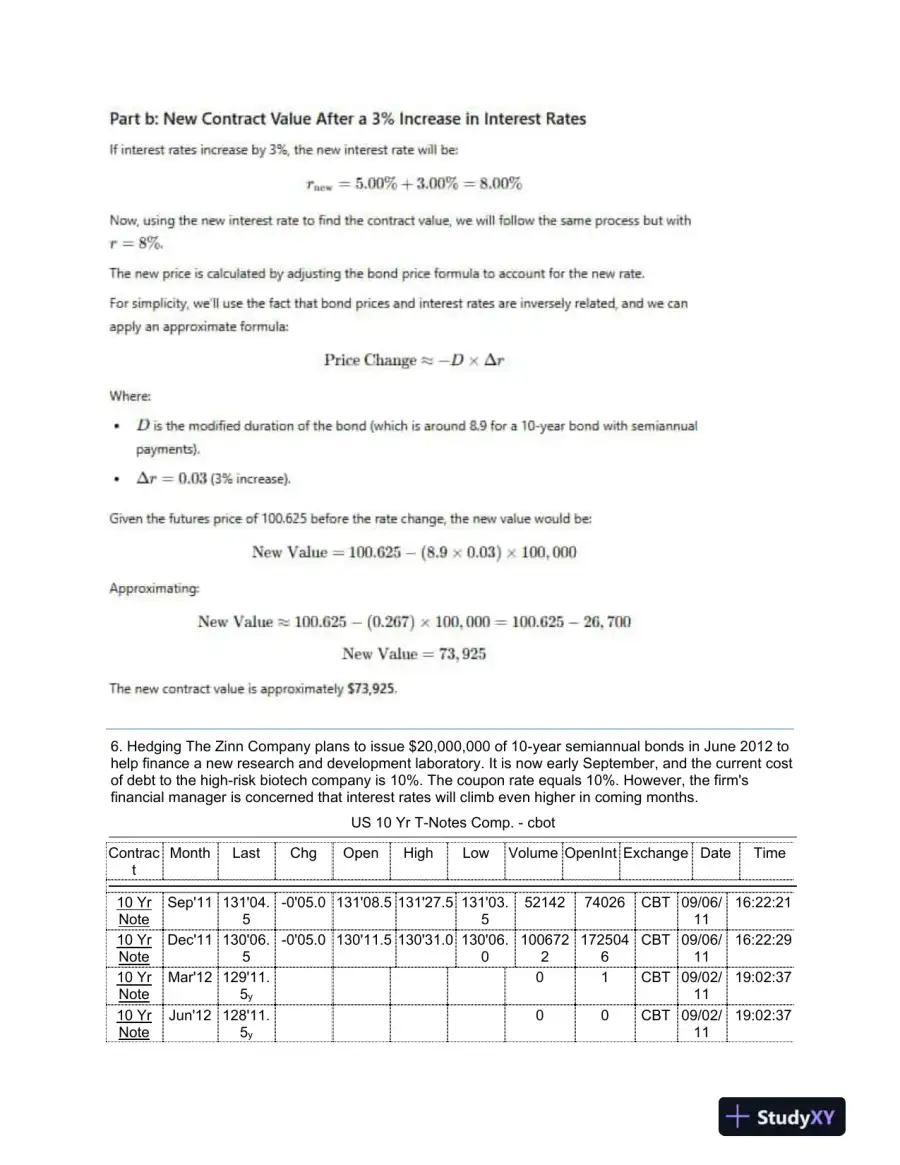 6.HedgingThe Zinn Company plans to issue $20,000,000 of 10-year semiannual bonds in June 2012 tohelp finance a new research and development laboratory. It is now early September, and the current costof debt to the high-risk biotech company is 10%. The coupon rate equals 10%. However, the firm'sfinancial manager is concerned that interest rates will climb even higher in coming months.US 10 Yr T-Notes Comp.-cbotContractMonthLastChgOpenHighLowVolumeOpenIntExchangeDateTime10 YrNoteSep'11131'04.5-0'05.0131'08.5131'27.5131'03.55214274026CBT09/06/1116:22:2110 YrNoteDec'11130'06.5-0'05.0130'11.5130'31.0130'06.010067221725046CBT09/06/1116:22:2910 YrNoteMar'12129'11.5y01CBT09/02/1119:02:3710 YrNoteJun'12128'11.5y00CBT09/02/1119:02:37
Page 6
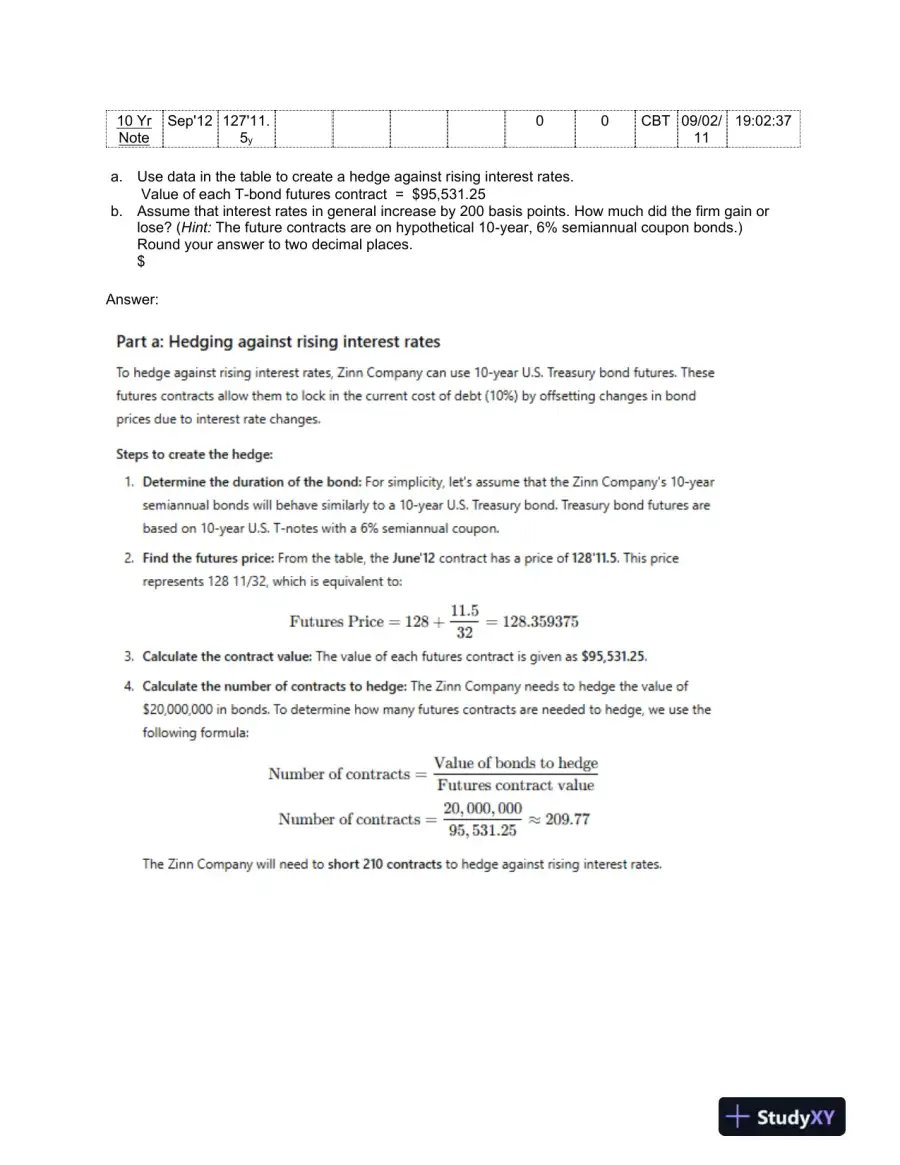 10 YrNoteSep'12127'11.5y00CBT09/02/1119:02:37a.Use data in the table to create a hedge against rising interest rates.Value of each T-bond futures contract= $95,531.25b.Assume that interest rates in generalincrease by 200 basis points. How much did the firm gain orlose? (Hint:The future contracts are on hypothetical 10-year, 6% semiannual coupon bonds.)Round your answer to two decimal places.$Answer:
13 more pages in the full document
Unlock it once and it stays in your library, ready to chat with or turn into flashcards.
Unlock the full documentMore Finance study materials
See all Textbook Guides
Solution Manual For Investments, 12th Edition
Finance
314 pages161downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, 8th Edition
Finance
851 pages158downloadsFeb 2025 Textbook Guides
Solution Manual for Financial Institutions Management: A Risk Management Approach, 8th Edition
Finance
486 pages154downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, Arab World Edition
Finance
373 pages148downloadsFeb 2025 Textbook Guides
Multinational Financial Management, Study Guide, 6th Edition Solution Manual
Finance
278 pages146downloadsFeb 2025 Textbook Guides
Financial Markets and Institutions, 7th Edition Solution Manual
Finance
194 pages136downloadsFeb 2025 Certification Guides
Wiley Finra Series 3 Exam Review (2019)
Finance
253 pages131downloadsFeb 2025 Exam Guides
Test Bank For Essentials of Investments, 8th Edition
Finance
368 pages130downloadsFeb 2025
Study this document with CramX
Once it is in your library, every tool can work from it.