
Practice Problems
Pension Plan Accounting And Analysis: Winona Corp's Defined Benefit Pension Plan
- Finance
- 9 pages
- Shared May 2025
Understand pension plan accounting with this solved assignment.
Preview · 3 of 9 pages
100%
Page 1
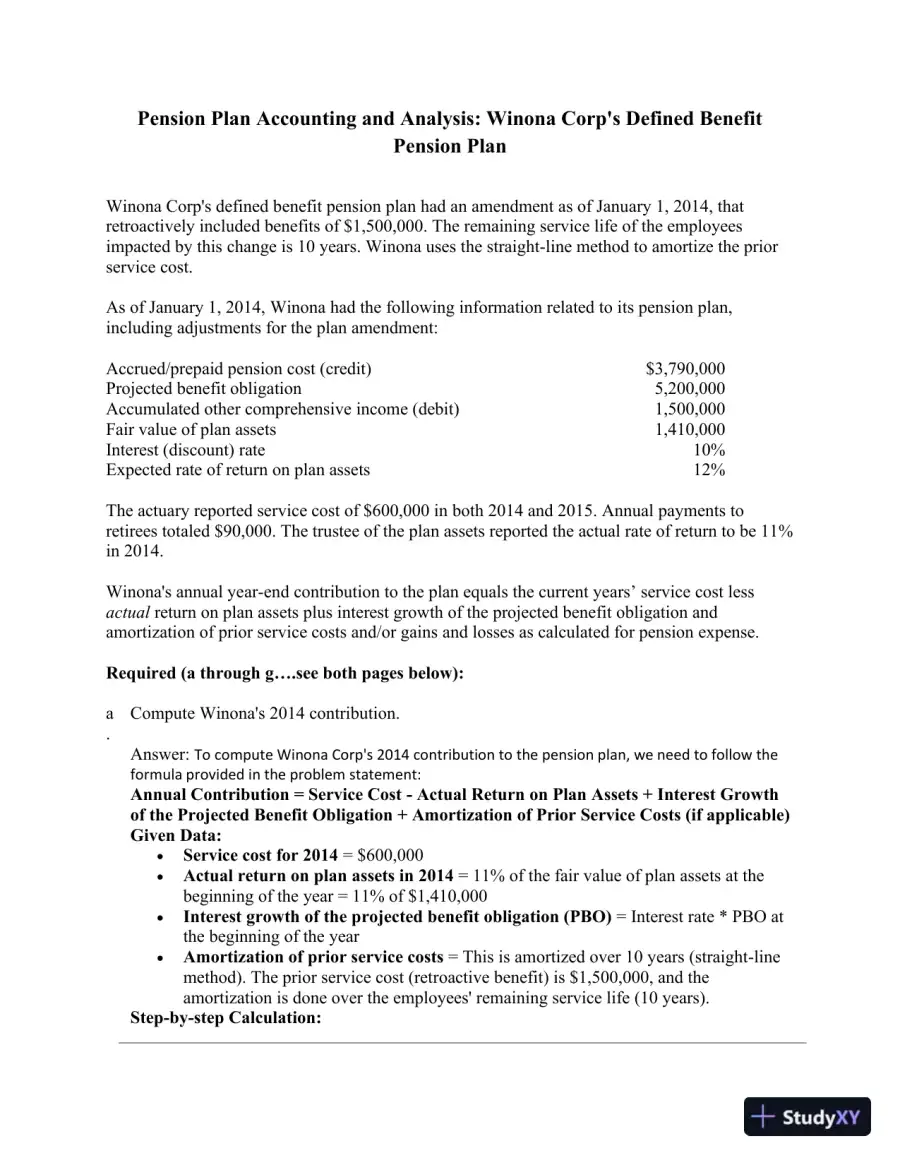 Pension Plan Accounting and Analysis: Winona Corp's Defined BenefitPension PlanWinona Corp's defined benefit pension plan had an amendment as of January 1, 2014, thatretroactively included benefits of $1,500,000. The remaining service life of the employeesimpacted by this change is 10 years.Winonauses the straight-line method to amortize the priorservice cost.As of January 1, 2014, Winona had the following information related to its pension plan,including adjustments for the plan amendment:Accrued/prepaid pension cost (credit)$3,790,000Projected benefit obligation5,200,000Accumulated other comprehensive income (debit)1,500,000Fair value of plan assets1,410,000Interest (discount) rate10%Expected rate of return on plan assets12%The actuary reported service cost of $600,000 in both 2014 and 2015. Annualpayments toretirees totaled $90,000. The trustee of the plan assets reported the actual rate of return to be 11%in 2014.Winona's annual year-end contribution to the plan equals the current years’service cost lessactualreturn on plan assets plus interest growth of the projected benefit obligation andamortization of prior service costs and/or gains and losses as calculated for pension expense.Required(a through g….see both pages below):a.Compute Winona's 2014contribution.Answer:To compute Winona Corp's 2014 contribution to the pension plan, we need to follow theformula provided in the problem statement:Annual Contribution = Service Cost-Actual Return on Plan Assets + Interest Growthof the Projected Benefit Obligation + Amortization of Prior Service Costs (if applicable)Given Data:•Service cost for 2014= $600,000•Actual return on plan assets in 2014= 11% of the fair value of plan assets at thebeginning of the year = 11% of $1,410,000•Interest growth of the projected benefit obligation (PBO)= Interest rate * PBO atthe beginning of the year•Amortization of prior service costs= This is amortized over 10 years (straight-linemethod). The prior service cost (retroactive benefit) is $1,500,000, and theamortization is done over the employees' remaining service life (10 years).Step-by-step Calculation:
Page 2
Page 3
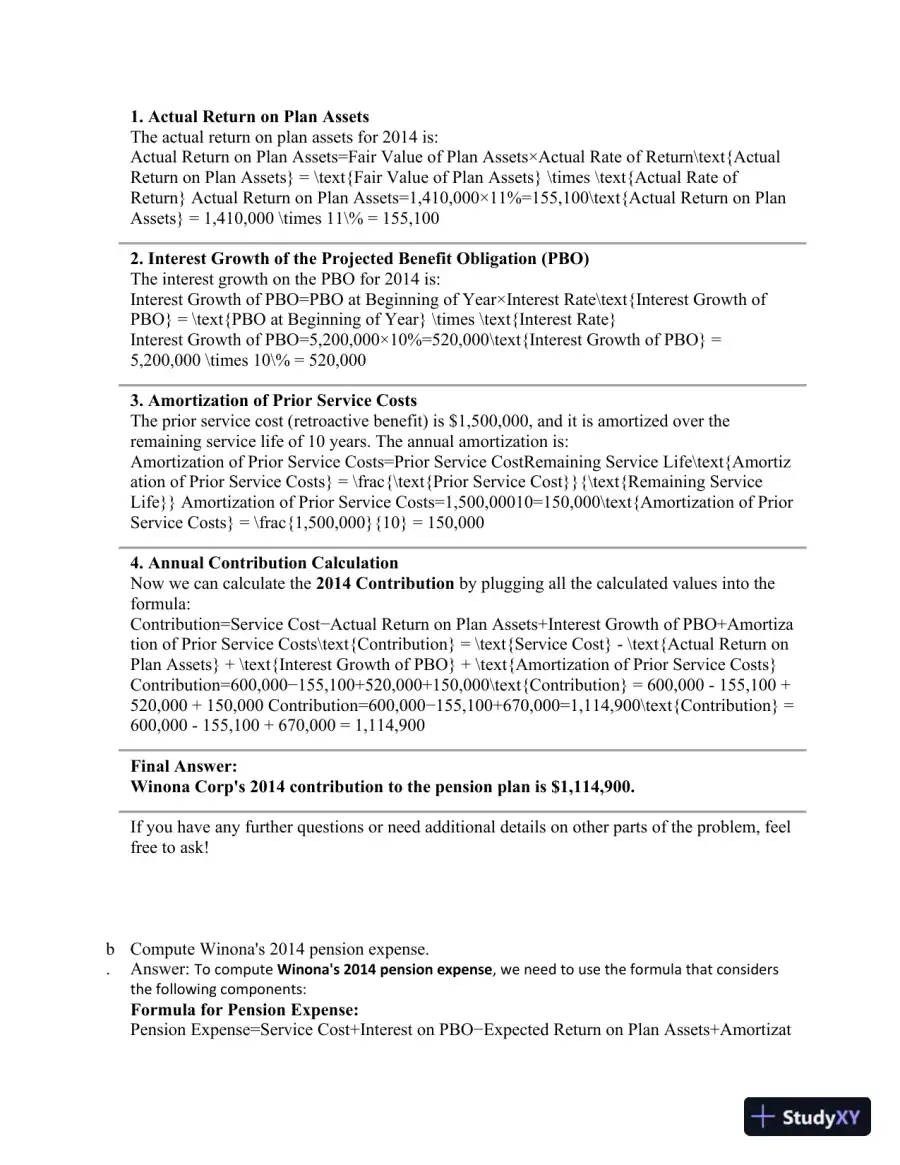 1. Actual Return on Plan AssetsThe actualreturn on plan assets for 2014 is:ActualReturnonPlanAssets=FairValueofPlanAssets×ActualRateofReturn\text{ActualReturn on Plan Assets} =\text{Fair Value of Plan Assets}\times\text{Actual Rate ofReturn} ActualReturnonPlanAssets=1,410,000×11%=155,100\text{Actual Return on PlanAssets} = 1,410,000\times 11\% = 155,1002. Interest Growth of the Projected Benefit Obligation (PBO)The interest growth on the PBO for 2014 is:InterestGrowthofPBO=PBOatBeginningofYear×InterestRate\text{Interest Growth ofPBO} =\text{PBO at Beginning of Year}\times\text{Interest Rate}InterestGrowthofPBO=5,200,000×10%=520,000\text{Interest Growth of PBO} =5,200,000\times 10\% = 520,0003. Amortization of Prior Service CostsThe prior service cost (retroactive benefit) is $1,500,000, and it is amortized over theremaining service life of 10 years. The annual amortization is:AmortizationofPriorServiceCosts=PriorServiceCostRemainingServiceLife\text{Amortization of Prior Service Costs} =\frac{\text{Prior Service Cost}}{\text{Remaining ServiceLife}} AmortizationofPriorServiceCosts=1,500,00010=150,000\text{Amortization of PriorService Costs} =\frac{1,500,000}{10} = 150,0004. Annual Contribution CalculationNow we can calculate the2014 Contributionby plugging all the calculated values into theformula:Contribution=ServiceCost−ActualReturnonPlanAssets+InterestGrowthofPBO+AmortizationofPriorServiceCosts\text{Contribution} =\text{Service Cost}-\text{Actual Return onPlan Assets} +\text{Interest Growth of PBO} +\text{Amortization of Prior Service Costs}Contribution=600,000−155,100+520,000+150,000\text{Contribution} = 600,000-155,100 +520,000 + 150,000 Contribution=600,000−155,100+670,000=1,114,900\text{Contribution} =600,000-155,100 + 670,000 = 1,114,900Final Answer:Winona Corp's 2014 contribution to the pension plan is $1,114,900.If you have any further questions or need additional details on other parts of the problem, feelfree to ask!b.Compute Winona's 2014 pension expense.Answer:To computeWinona's 2014 pension expense, we need to use the formula that considersthe following components:Formula for Pension Expense:PensionExpense=ServiceCost+InterestonPBO−ExpectedReturnonPlanAssets+Amortizat
6 more pages in the full document
Unlock it once and it stays in your library, ready to chat with or turn into flashcards.
Unlock the full documentMore Finance study materials
See all Textbook Guides
Solution Manual For Investments, 12th Edition
Finance
314 pages161downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, 8th Edition
Finance
851 pages158downloadsFeb 2025 Textbook Guides
Solution Manual for Financial Institutions Management: A Risk Management Approach, 8th Edition
Finance
486 pages154downloadsFeb 2025 Exam Guides
Test Bank for Principles of Managerial Finance, Arab World Edition
Finance
373 pages148downloadsFeb 2025 Textbook Guides
Multinational Financial Management, Study Guide, 6th Edition Solution Manual
Finance
278 pages146downloadsFeb 2025 Textbook Guides
Financial Markets and Institutions, 7th Edition Solution Manual
Finance
194 pages136downloadsFeb 2025 Certification Guides
Wiley Finra Series 3 Exam Review (2019)
Finance
253 pages131downloadsFeb 2025 Exam Guides
Test Bank For Essentials of Investments, 8th Edition
Finance
368 pages130downloadsFeb 2025
Study this document with CramX
Once it is in your library, every tool can work from it.