

Financial Accounting: An Integrated Approach, 5th Edition Solution Manual
- Accounting
- 42 pages
- Shared May 2025
Need help understanding your textbook? Financial Accounting: An Integrated Approach, 5th Edition Solution Manual simplifies complex problems with clear solutions.
Preview 13 of 42 pages
See the first 13 pages exactly as they appear in the document.
Page 1 Read page 1 as text
Chapter 1 Introduction to financial accounting Practice Problems Practice Problem A 1 Account Classification Cash at bank Asset Inventory Asset Sales Revenue Wages Expense Cost of goods sold Expense Share capital Equity Accounts payable Liability 2 Income Statement For the year ending 30 June 2012 $ Sales 210,000 Cost of goods sold (70,000) Gross profit 140,000 Wages (40,000) Net Profit 100,000 3 Balance Sheet As at 30 June 2012 Assets Liabilities and shareholders’ equity $ $ Cash at bank 210,000 Accounts payable 30,000 Inventory 60,000 Share capital 140,000 Retained profits 100,000 * 270,000 270,000 *Opening retained profit + profit –dividend = closing balance retained profit (0 + 100,000 – 0 = 100,000)
Page 2 Page 3 Read page 3 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 2 Practice Problem B 1 Accrual profit = total sales – total expenses = $750,000 + 260,000 – 580,000 – 240,000 = $190,000 2 Sales revenue = 2,000 x $8 = $16,000 Cost of goods sold = 2,000 x $5 = $10,000 Practice Problem C Shareholders’ equity = Assets – Liabilities = (Property, Plant and Equipment $1,500,000 + Accounts Receivable $400,000 + Cash $100,000 + Inventory $500,000) – (Bank loan $250,000 + Wages Payable $90,000) = $2,500,000 – 340,000 = $2,160,000
Page 4 Read page 4 as text
Chapter 2 Measuring and evaluating financial position and financial performance Practice Problems Practice Problem A $ Sales (300,000 + 100,000) 400,000 COGS (70,000) Other operating expenses (80,000 + 30,000) (110,000) Net profit before ta x 220,000 Practice Problem B PSM Limited Balance sheet as at 30 June 2012 $000 Current a ssets Cash 11,636 Accounts receivable 47,515 Inventory 66,479 Prepayments 3,958 Investments 3,371 132,959 Non - current assets Other receivable 361 Investments 2,087 Property, plant and equipment 67,760 Other long term assets 42,742 112,950 Total assets 245,909 Current liabilities Accounts payable 43,091 Provisions for employee entitlements 30,919 74,010 Non - current liabilities Long-term borrowings 30,866 Provisions for employee entitlements 3,969 34,835 Total liabilities 108,845 Net assets 137,064 Shareholders’ equity Share capital 108,518 Retained profits 28,546 Total shareholders’ equity 137,064
Page 5 Read page 5 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 2 Practice Problem C 1 NE 2 +Revenue, +Net Profit 3 +Expense, –Net Profit 4 NE 5 NE 6 NE 7 NE 8 +Revenue, +Expense, +Net Profit 9 +Expense, –Net Profit 10 NE 11 +Expense, –Net Profit 12 NE Practice Problem D Income Statement for the Month of September 2011 $ $ Sales 30,000 Expenses: Wages 7,000 Clea ning 1,000 Rent 2,000 10,000 Net Profit 20,000 Balance Sheet as at 30 September 2011 $ $ Cash 1 102,000 Accounts Payable 1,000 Accounts Receivable 2 19,000 1,000 Shareholders’ equity Share capital 100,000 Retained profits 3 20,000 120,000 121,000 121,000 1 100,000 – 2,000 + 11,000 – 7,000 = 102,000 2 30,000 – 11,000 = 19,000 3 As there is no opening retained profits and no dividends, it is profit figure from the income statement
Page 6 Read page 6 as text
Chapter 3 The double-entry system Practice Problems Practice Problem A 1 ASSETS = LIABILITIES + SHAREHOLDERS’ EQUITY Cash Accounts receivable Inventory Accounts payable Rent payable Tax payable Retained profits Revenue Expenses $ $ $ $ $ $ $ $ $ 1 +10,000 +10,000 2 +9,600 -9,600 3 +6,100 +6,100 4 -6,300 -6,300 5 -6,400 -6,400 6 2,400 -2,400 7 -2,900 -2,900 8 350 -350 9 -450 -450 Total -50 400 -300 -200 -500 350 -450 10,000 -9,150 50 = 50 NB. Increases in expenses have been entered as minus figures. 2 Flashy Fashions Ltd Income statement For the year ended 30 September 2012 $ Sales 10,000 Less Cost of goods sold 6,400 Gross profit 3,600 Less Operating Expenses Rent 2,400 Profit before tax 1,200 Less tax expense 350 Net Profit 850 Flashy Fashions Ltd Balance sheet as at 30 September 2012 Current Assets $ Current Liabilities $ Cash 750 Accounts Payable 400 Accounts Receivable 800 Tax Payable 350 Inventory 600 Prepaid rent 200 Shareholders’ equity Share Capital 500 Retained Profits 1,100 2,350 2,350
Page 7 Read page 7 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 2 Practice Problem B 1 $160,000. 2 $105,000. 3 $180,000. 4 $140,000.
Page 8 Read page 8 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 3 Practice Problem C 1 Assets = Liabilities + Shareholders’ e quity Cash A/R Inventory Pre - payments Equip Accum. Dep A/P Loan Share Capital Opening Retained Profits Revenues Expenses Dividends 90 , 000 106 , 000 118 , 000 45 , 000 400 , 000 – 125 , 000 110 , 000 240 , 000 200 , 000 84 , 000 1 +23 , 000 – 23 , 000 2 +80 , 000 +80 , 000 3 +76 , 000 – 32 , 000 +76 , 000 – 32 , 000 4 – 4 , 000 – 4 , 000 5 – 60 , 000 – 60 , 000 6 – 7 , 000 – 7 , 000 7 – 9 , 000 – 9 , 000 8 – 13 , 000 – 13 , 000 9 – 28 , 000 +28 , 000 10 – 6 , 000 – 6 , 000 11 – 36 , 000 – 36 , 000 43,000 159,000 114,000 36,000 400,000 –129,000 74,000 180,000 280,000 84,000 76,000 –65,000 –6,000
Page 9 Read page 9 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions Practice Problem C (cont’d) 2 Newcombe Ltd Income Statement for the month ended 30 June 2012 $ $ Sales 76,000 Cost of goods sold (32 , 000) Gross profit 44 , 000 Operating expenses Wages 13 , 000 Prepaid expenses 9 , 000 Administrative 7 , 000 Depreciation 4 , 000 (33 , 000) Net profit 11,000 Newcombe Ltd Statement of retained profits for the month ended 30 June 2012 $ Opening retained profits 84 , 000 Add net profit for the month 11 , 000 95 , 000 Less dividends declared (6 , 000) Closing retained profits 89,000 Newcombe Ltd Balance Sheet as at 30 June 2012 Current assets $ Current liabilities $ Cash 43 , 000 Accounts payable 74 , 000 Accounts receivable 159 , 000 Inventory 114 , 000 Noncurrent liabilities Prepayments 36 , 000 Long - term loan 180 , 000 352,000 254,000 Noncurrent assets Shareholders’ equity Equipment 400 , 000 Share capital * 280 , 000 Accumulated depreciation (129 , 000) Retained profits 89 , 000 271 , 000 369 , 000 Total assets 623,000 Total liabilities and equity 623,000 3 Net Profit Total Assets Total Liabilities Shareholders’ Equity 1 No effect No effect No effect No effect 2 No effect Increase No effect Increase 3 Increase Increase No Effect Increase 4 Decrease Decrease No Effect Decrease 5 No Effect Decrease Decrease No Effect 6 Decrease Decrease No Effect Decrease 7 Decrease Decrease No Effect Decrease 8 Dec rease Decrease No Effect Decrease 9 No Effect No Effect No Effect No Effect 10 No Effect Decrease No Effect Decrease 11 No Effect Decrease Decrease No Effect NB: If Net Profit increases it increases to Retained Profits and therefore Shareholders’ Equity increases.
Page 10 Read page 10 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 5 4 1 DR Cash $23,000 CR Accounts receivable $23,000 2 DR Cash 80,000 CR Share capital 80,000 3 DR Cost of Goods Sold 32,000 CR Inventory 32,000 DR Accounts receivable 76,000 CR Sales revenue 76,000 4 DR Depreciation expe nse 4,000 CR Accumulated depreciation 4,000 5 DR Long - term loan 60,000 CR Cash 60,000 6 DR Administrative expense 7,000 CR Cash 7,000 7 DR Prepayments 9,000 CR Expense 9,000 8 DR Wages 13,000 CR Cash 13,000 9 DR Inventor y 28,000 CR Cash 28,000 10 DR Retained profits 6,000 CR Cash 6,000 11 DR Accounts payable 36,000 CR Cash 36,000
Page 11 Read page 11 as text
Chapter 4 Record-keeping Practice Problems Practice Problem A 1 No transaction since no exchange yet. 2 Yes, an exchange of money for advice. 3 No transaction for Bartlett as the exchanges that changed share price were between investors, not involving Bartlett. 4 Yes, an exchange of advertising received for a promise to pay, so a credit transaction. 5 Yes, for same reason as 4 – work received in exchange for a promise to pay for it. 6 Yes, an exchange of a sort. The teenager received cash and the company got some benefit (e.g. avoided a later lawsuit or other problem). 7 Yes, goods received in exchange for a combination of cash and promise to pay. 8 Yes, an exchange of cash for a removal of the promise to pay. 9 Yes, an exchange of cash for political benefit. The illegality doesn’t change the fact that a transaction happened. 10 Yes, an exchange of cash for a promise to repay it. Practice Problem B 1 Journal entries: Hoad Ltd General journal No Description Post ref Debits Credits $ $ 1 Cash 1 200,000 Share capital 21 200,000 2 Inventory 3 20,000 Cash 1 20,000 3 Rent expense 31 4,000 Cash 1 4,000 4 Inventory 3 30,000 Accounts payable 11 30,000 5 Advertising expense 32 1,000 Expenses payable 12 1,000 6 Accounts receivable 2 90,000 Sales 26 90,000 Cost of goods sold 30 40,000 Inventory 3 40,000 7 Accounts payable (current) 11 25,000 Cash 1 25,000
Page 12 Read page 12 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 2 8 Cash 1 30,000 Accounts receivable 2 30,000 9 Wages expense 33 15,000 Cash 1 15,000 10 Sales commission 34 900 Cash 1 900 11 Office equipment 6 6,000 Cash 1 3,000 Accounts payable (noncurrent) 16 3,000 12 Wages expense 33 2,000 Expenses payable 12 2,000 2 General ledger postings: Hoad Ltd General Ledger Cash 1 1 Share capital 200,000 2 Inventory 20,000 8 Accounts receivable 30,000 3 Rent 4,000 7 Accounts payable 25,000 9 Wages 15,000 10 Sales commission 900 11 Office equipment 3,000 Balance c/d 162,100 230,000 230,000 Balance b/d 162,100 Accounts Receivable 2 6 Sales 90,000 8 Cash 30,000 Balance c/d 60,000 90,000 90,000 Balance b/d 60,000
Page 13 Read page 13 as text
Trotman: Financial Accounting 5e – Practice Problem Solutions 3 Inventory 3 2 Cash 20,000 6 Cost of goods sold 40,000 4 Accounts payable 30,000 Balance c/d 10,000 50,000 50,000 Balance b/d 10,000 Office Equipment 6 11 Cash 3,000 Accounts payable (noncurrent) 3,000 6,000 Accounts Payable—Current 11 7 Cash 25,000 4 Inventory 30,000 Balance c/d 5,000 30,000 30,000 Balance b/d 5,000 Expenses Payable 12 5 Advertising 1,000 12 Wages 2,000 3,000 Accounts Payable—Noncurrent 16 11 Office equipment 3,000 Share Capital 21 1 Cash 200,000
29 more pages in the full document
Unlock it once and it stays in your library, ready to chat with or turn into flashcards.
Unlock the full documentMore Accounting study materials
See all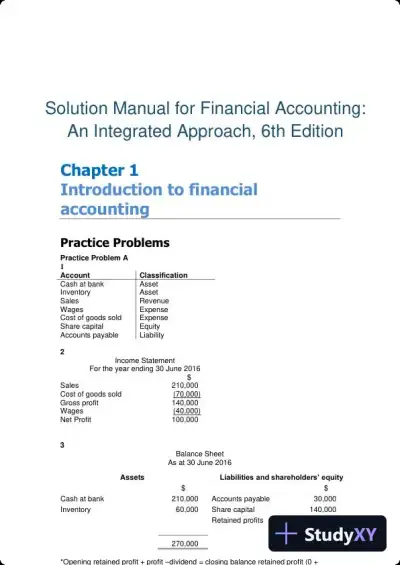 Textbook Guides
Solution Manual for Financial Accounting: An Integrated Approach, 6th Edition
Accounting
150 pages122downloadsFeb 2025 Textbook Guides
Introduction to Financial Accounting, 11th Edition Solution Manual
Accounting
524 pages173downloadsFeb 2025 Textbook Guides
Solution Manual For International Accounting, 4th Edition
Accounting
309 pages161downloadsFeb 2025 Textbook Guides
Solution Manual For Managerial Accounting, 7th Edition
Accounting
361 pages159downloadsFeb 2025 Class Notes
 For Advanced Accounting, 4th Edition
Accounting
149 pages159downloadsFeb 2025 Textbook Guides
Financial Accounting 6th Canadian Edition Solution Manual
Accounting
867 pages156downloadsFeb 2025 Textbook Guides
Accounting Theory, 7th Edition Solution Manual
Accounting
325 pages153downloadsFeb 2025 Textbook Guides
Financial Accounting, 9th Edition Solution Manual
Accounting
1024 pages134downloadsFeb 2025
Study this document with CramX
Once it is in your library, every tool can work from it.